W-2 employees can build wealth without a high salary by controlling cash flow, getting rid of expensive debt, building a pool of money they control, and putting that money to work over time. Income matters, but what you do with the gap between what you earn and what you spend matters more. That’s the focus of my Financial Freedom Program and resources.
I hear the same thing from a lot of people with regular jobs: “I’ll start building wealth once I make more.” The problem is that spending tends to rise with income. If the habits aren’t there at $50,000, they usually aren’t there at $100,000 either. So here’s what I’d do on a W-2 paycheck.
Step 1: Know your numbers
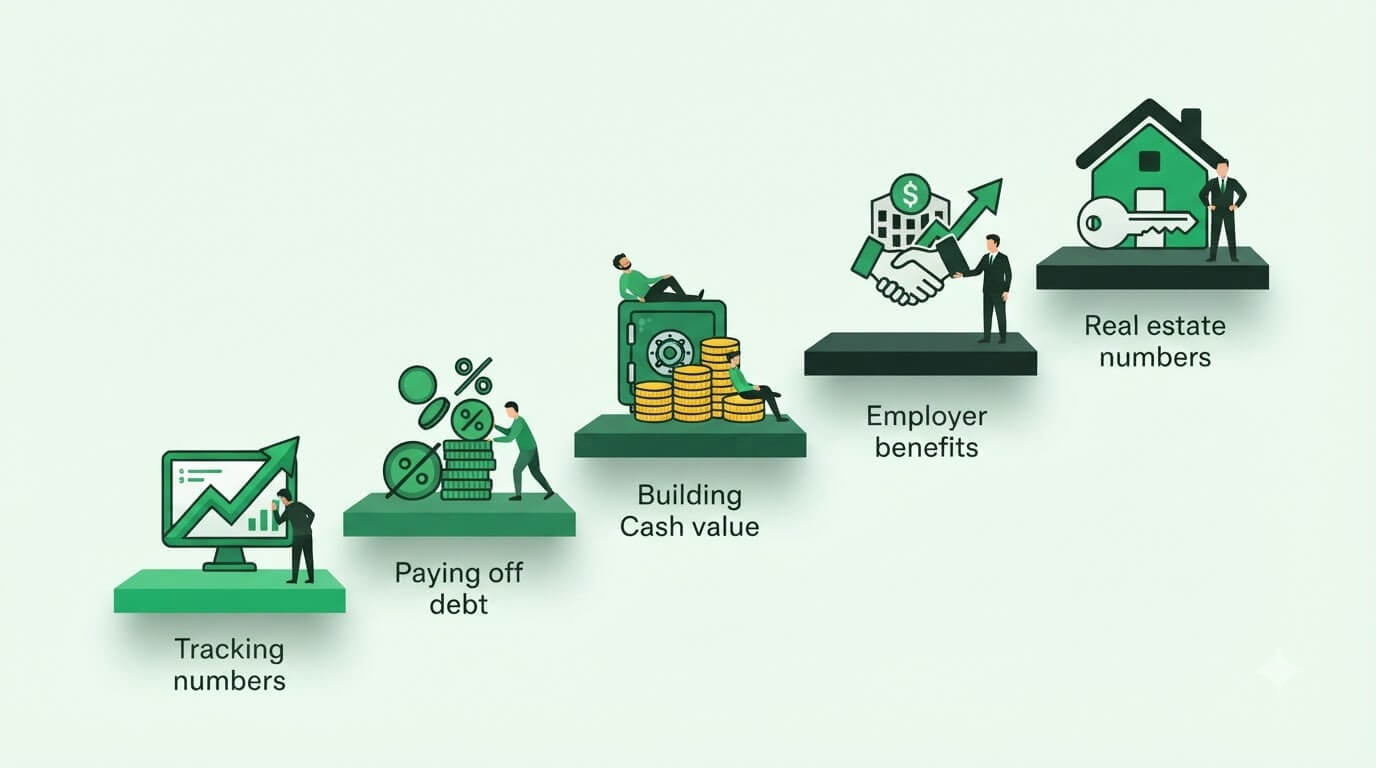
Before anything else, you need four numbers: monthly income, monthly expenses, total debt, and cash flow, which is what’s left after expenses. Most people guess at these. Write them down for real, using your bank statements from the last three months instead of your memory. The download on my resources page makes this easier.
Cash flow is the most important of the four. It’s the fuel for everything else on this list. If it’s negative, your first job is to fix that by trimming expenses, adding income, or both.
Step 2: Stop paying the bank so much
High interest debt eats wealth before it can grow. Credit cards, car loans, and even a mortgage in its early years send a big share of your money to lenders. Paying these down faster frees up cash flow every month. Velocity Banking is one strategy I use with W-2 families who have steady surplus income, because it uses a line of credit to send larger chunks at debt.
Step 3: Build money you control
Once debt is under control, the next question is where the freed up cash goes. Many W-2 earners send everything into retirement accounts they can’t touch for decades. Retirement savings matter, but you also need liquidity you can reach now. For many of my clients, that’s a properly designed whole life policy used for Infinite Banking, where cash value keeps growing even while you borrow against it.
Step 4: Use what your job already gives you
A W-2 job often comes with benefits people leave on the table. If your employer matches retirement contributions, contribute at least enough to get the full match. Review your health and insurance benefits once a year. And look at your tax situation. Most W-2 workers just file and move on, but some planning ahead of time can keep more money in your pocket.
Step 5: Build credit and a second income stream
Strong credit gives you better rates and more options. A side business or real estate gives you income that doesn’t depend on one paycheck. Several of my clients have started businesses or bought rental property after getting their debt handled. If real estate interests you, my post on real estate investing with Velocity Banking and Infinite Banking shows how these pieces connect.
| Area | Typical W-2 Approach | Cash Flow First Approach |
|---|---|---|
| Budget | Rough idea of spending | Four numbers tracked every month |
| Debt | Minimum payments on a set schedule | Targeted payoff to free up cash flow |
| Savings | Whatever is left, if anything | A planned amount going to money you control |
| Retirement | The only long term plan | One part of a bigger plan that includes liquidity |
| Extra income | Waiting for a raise | Side business or real estate built over time |
The part nobody wants to hear
This takes time. Wealth on a W-2 is built over years, not months. You’ll have months where nothing seems to move, and months where an unexpected bill knocks you back. The families I’ve seen succeed are the ones who stuck to the plan through those stretches instead of starting over every time something went wrong.
It also works better with help. My Financial Freedom Program pairs one-on-one coaching with a clear plan, and each coaching call you invest in can be applied toward the program as a discount. You don’t need a huge salary to start. You need a plan and the discipline to follow it.
Build wealth on the income you have now
Let’s go through your four numbers together and build a step by step plan that fits your paycheck.
Start Your PlanFrequently Asked Questions
Can you build wealth on a $50,000 salary?
Yes, if you keep your expenses below your income and put the difference to work consistently. Cash flow and time matter more than the size of the paycheck.
Should W-2 employees pay off debt or invest first?
It depends on your interest rates and your employer benefits. Many people capture any retirement match first and then focus hard on high interest debt before investing more.
What is the Financial Freedom Program?
It’s my coaching program that combines one-on-one guidance with a full plan for debt payoff, cash flow, and long term wealth building.