Whole life insurance cash value builds wealth slowly and steadily, through guaranteed growth, dividends, and the option to borrow against it without stopping that growth. It won’t make you rich overnight. What it gives you is a growing pool of money you control, plus a death benefit for your family. My Infinite Banking page explains how I use it with clients.
People hear “life insurance builds wealth” and either get excited or roll their eyes. Both reactions usually come from not knowing how the cash value works. So here’s the plain version.
What cash value is
A whole life policy has two parts. There’s the death benefit, which pays your family when you pass away. And there’s the cash value, which is a savings component that grows inside the policy while you’re alive. Part of every premium you pay goes into that cash value.
Term insurance doesn’t have this. You pay for coverage over a set number of years, and when the term ends, there’s nothing left. Whole life lasts your entire life and builds value along the way.
The three ways cash value grows
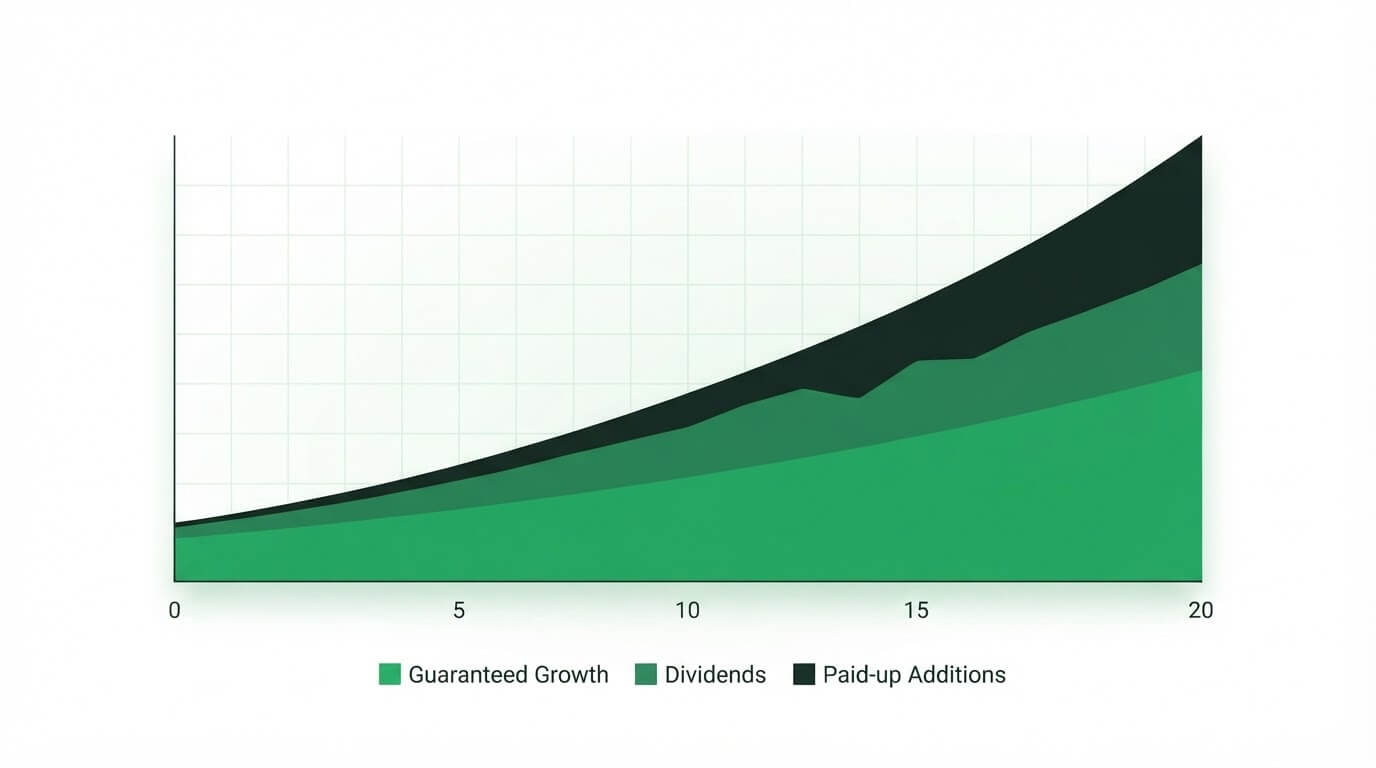
- Guaranteed growth. The insurance company guarantees that the cash value will increase each year according to the contract.
- Dividends. Mutual insurance companies are owned by their policyholders, and they can pay dividends when they perform well. Dividends aren’t guaranteed, but the major mutual companies have long histories of paying them.
- Paid-up additions. Extra money you put into the policy buys small pieces of fully paid insurance, each with its own cash value. This is how you speed things up.
Put those together over years, and the cash value compounds. The early years are slow because a bigger share of your premium goes to insurance costs. Patience pays off here more than almost anywhere else in personal finance.
Where the wealth building really happens
Here’s the part many people miss. The growth rate alone isn’t the whole story. The guaranteed growth in a whole life policy is real, but it’s modest compared to what long term market investing can produce.
The bigger impact comes from how you use the cash value. When you take a policy loan, you borrow from the insurance company using your cash value as collateral. Your cash value stays in the policy and keeps growing. Meanwhile, the borrowed money can go to work somewhere else, like paying off a high interest debt, funding a down payment, or starting a business.
So instead of one pool of money doing one job, you have money growing inside the policy while the loan funds something else. That’s the engine behind using policy loans as part of an Infinite Banking strategy.
| Feature | Term Life | Whole Life (Designed for Cash Value) | IUL |
|---|---|---|---|
| Cash value | None | Yes, grows every year | Yes, tied to index crediting |
| Guarantees | Coverage for the term only | Guaranteed growth and death benefit | Fewer guarantees, costs can change |
| Dividends | No | Yes, from mutual companies | No |
| Coverage length | Set number of years | Your whole life | Depends on funding |
| Fit for Infinite Banking | No | Yes, when designed properly | I don’t recommend it |
Why policy design changes everything
Two whole life policies with the same premium can build cash value at very different speeds. A policy built mainly for a big death benefit will be slow. A policy built for Infinite Banking uses a smaller base premium and puts more money into a paid-up additions rider, which pushes cash value up faster in the early years.
I always recommend going with one of the major mutual companies. I also want to be clear that I don’t endorse IUL for this. If you want the deeper version, my post on whole life insurance and Infinite Banking covers how the two connect, and my list of Infinite Banking mistakes covers what goes wrong when the design is off.
The legacy side of cash value
For the families I work with, wealth isn’t only about what you have today. It’s about what you leave your children. A whole life policy does both jobs. You use the cash value while you’re alive, and the death benefit passes to your family when you’re gone. That’s a big part of why I talk about building a kingdom instead of a bank balance.
See how your cash value could grow
Get a real policy illustration built around your budget and goals, and we’ll walk through the numbers line by line.
Schedule a ConsultationFrequently Asked Questions
Is whole life insurance cash value a good investment?
I’d call it a savings and financing tool more than an investment. The growth is steady and protected, but modest. Its biggest strength is liquidity and control, not high returns.
Can I withdraw my cash value?
Yes, you can withdraw or borrow against it. Borrowing is usually the better route for Infinite Banking because your full cash value stays in the policy and keeps compounding.
How long does it take for cash value to grow?
The first several years are slow. A policy designed with a paid-up additions rider builds faster, but you should plan to hold it for many years to see meaningful results.