A good cash flow management strategy only works if it’s built around how your money actually arrives — and that’s exactly where 1099 contractors and W-2 employees part ways. Velocity Banking was originally explained using a steady paycheck as the example, which makes sense for a W-2 household but leaves out anyone whose income shows up in uneven chunks. If that’s you, the strategy doesn’t stop working. It just needs a different setup.
The W-2 Version, Quickly
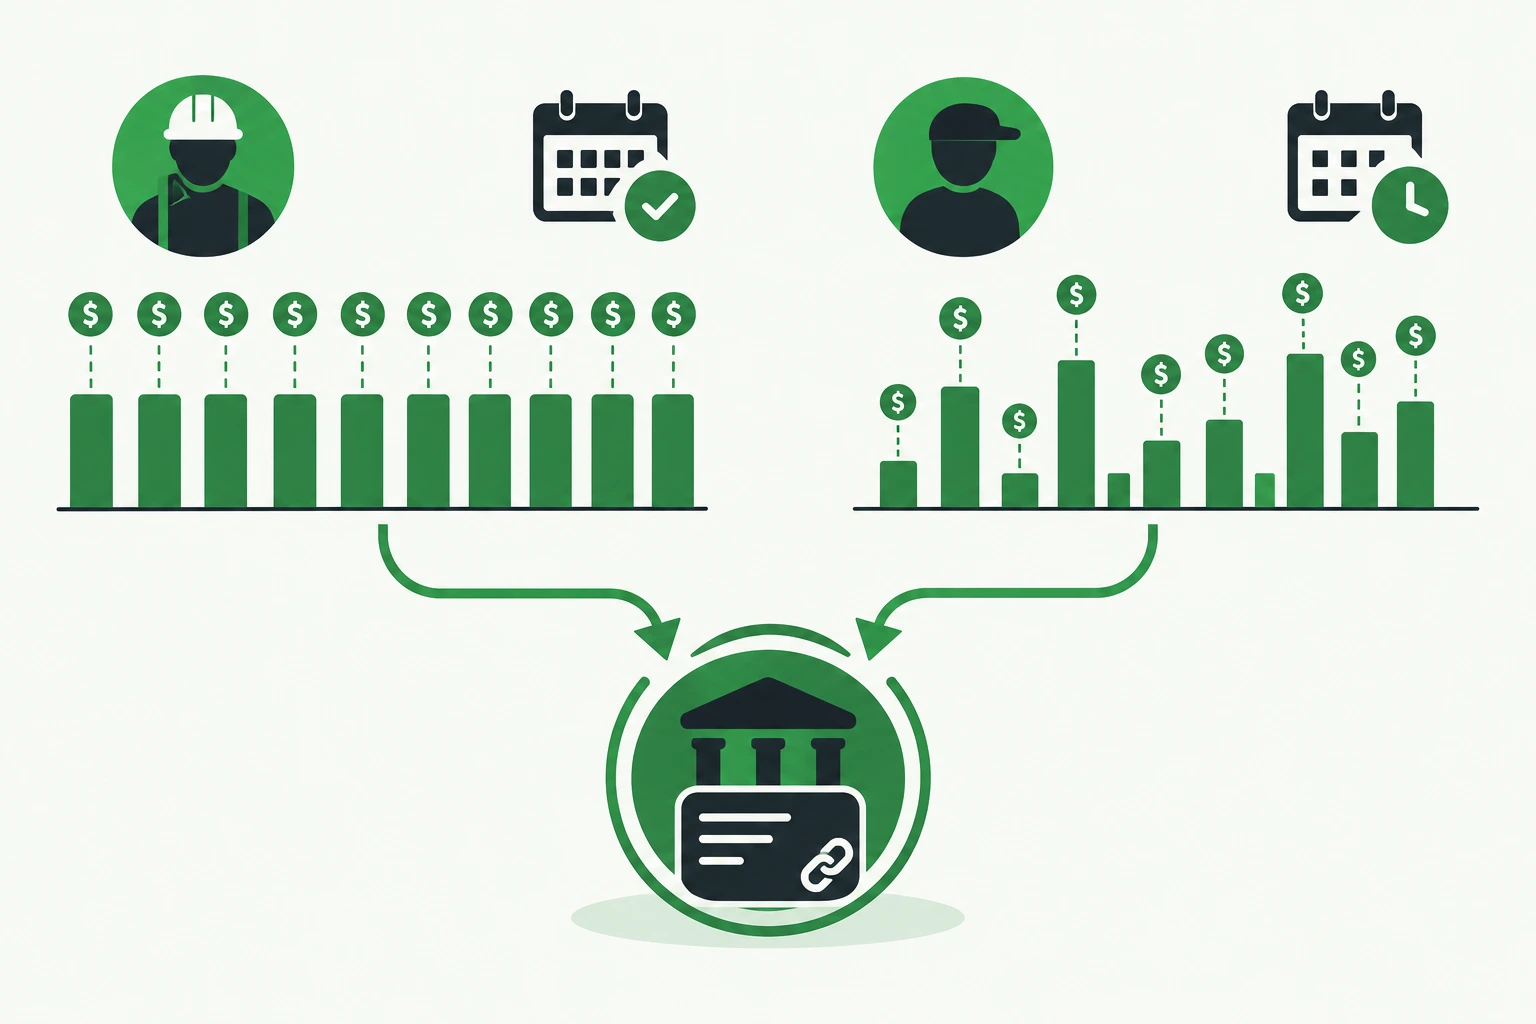
A W-2 employee’s income is predictable: the same amount lands on the same schedule, taxes are already withheld, and there’s rarely a surprise. That predictability is what makes the classic Velocity Banking cadence — deposit income into the line of credit, let it sit, pay expenses from it, watch the balance drop between paychecks — so easy to plan around. The whole strategy assumes you know roughly what’s coming in and when.
That predictability is exactly why most explanations of Velocity Banking default to the W-2 example — it’s the simplest version to teach, and the math is easy to follow when the deposit amount barely changes from month to month. Contractors reading those same examples often assume the strategy just isn’t built for them. It is. It just needs a second layer of planning underneath it.
Why 1099 Income Breaks That Assumption
Contractor income doesn’t follow a calendar. A big invoice might clear in week two and nothing shows up again until week six. There’s no employer withholding taxes for you, which means a portion of every payment actually belongs to the IRS come quarterly estimated tax time, not to your mortgage payoff plan. Run everything through a HELOC the same way a W-2 household would, and you risk pushing the balance down aggressively in a good month, only to be stuck carrying a larger balance than planned when the next payment is late.
1099 vs. W-2: What Actually Changes
| Factor | W-2 Employee | 1099 Contractor |
|---|---|---|
| Income pattern | Fixed, predictable schedule | Irregular, project or invoice-based |
| Tax withholding | Handled by employer | Self-managed, usually quarterly |
| Recommended cash buffer | Smaller, since income is reliable | Larger, to absorb slow months and tax payments |
| Chunking cadence | Can follow a set monthly rhythm | Better tied to invoice or contract timing |
| Risk if the line runs low | Lower, income arrival is consistent | Higher, next payment date isn’t guaranteed |
How Contractors Should Adjust the Strategy
The core mechanics of Velocity Banking don’t change for a 1099 contractor — the guardrails do. Setting aside estimated tax money before anything touches the line of credit has to come first, not last. Keeping a wider buffer on the HELOC, rather than chunking it down to near zero, gives you room to absorb a slow month without scrambling. And timing a chunk to line up with a confirmed invoice date, rather than an assumed one, keeps the strategy from outrunning your actual cash position.
This is also where combining tools can help. Some contractors pair Velocity Banking with a funded whole life policy specifically so they have a second, more stable source of capital during slow stretches, which our post on funding Velocity Banking with Infinite Banking walks through in more detail.
The Bottom Line for Contractors
Velocity Banking works for 1099 contractors, but treating it exactly like the W-2 version is where people get into trouble. Build the tax set-aside into your routine first, keep more room in the line than a salaried household would need, and let your invoice schedule — not a generic monthly plan — drive when you chunk payments down. Get those three things right, and irregular income stops being a reason to sit on the sidelines.
One more habit worth adopting: keep business income and personal spending running through separate lines if you can manage it, rather than mixing a contracting business’s cash flow with the same HELOC funding your mortgage payoff. It makes tax time simpler and makes it much easier to see, at a glance, how much of your line’s balance is really tied to the mortgage strategy versus day-to-day business expenses.
Frequently Asked Questions
Can self-employed contractors qualify for a HELOC?
Yes, though lenders typically ask for more income documentation, such as tax returns or profit and loss statements, compared to a W-2 applicant.
Should I set aside taxes before or after chunking my HELOC?
Before. Estimated tax money should be set aside first so it never gets treated as available cash flow for paying down the line.
How big of a buffer should a contractor keep on the line?
It depends on how irregular your income is, but a wider cushion than a salaried household would use is generally the safer approach.
Build a Cash Flow Management Strategy That Fits Contractor Income
Get a Velocity Banking setup built around how your income actually arrives, not a generic paycheck schedule.
Get Coaching for Contractors